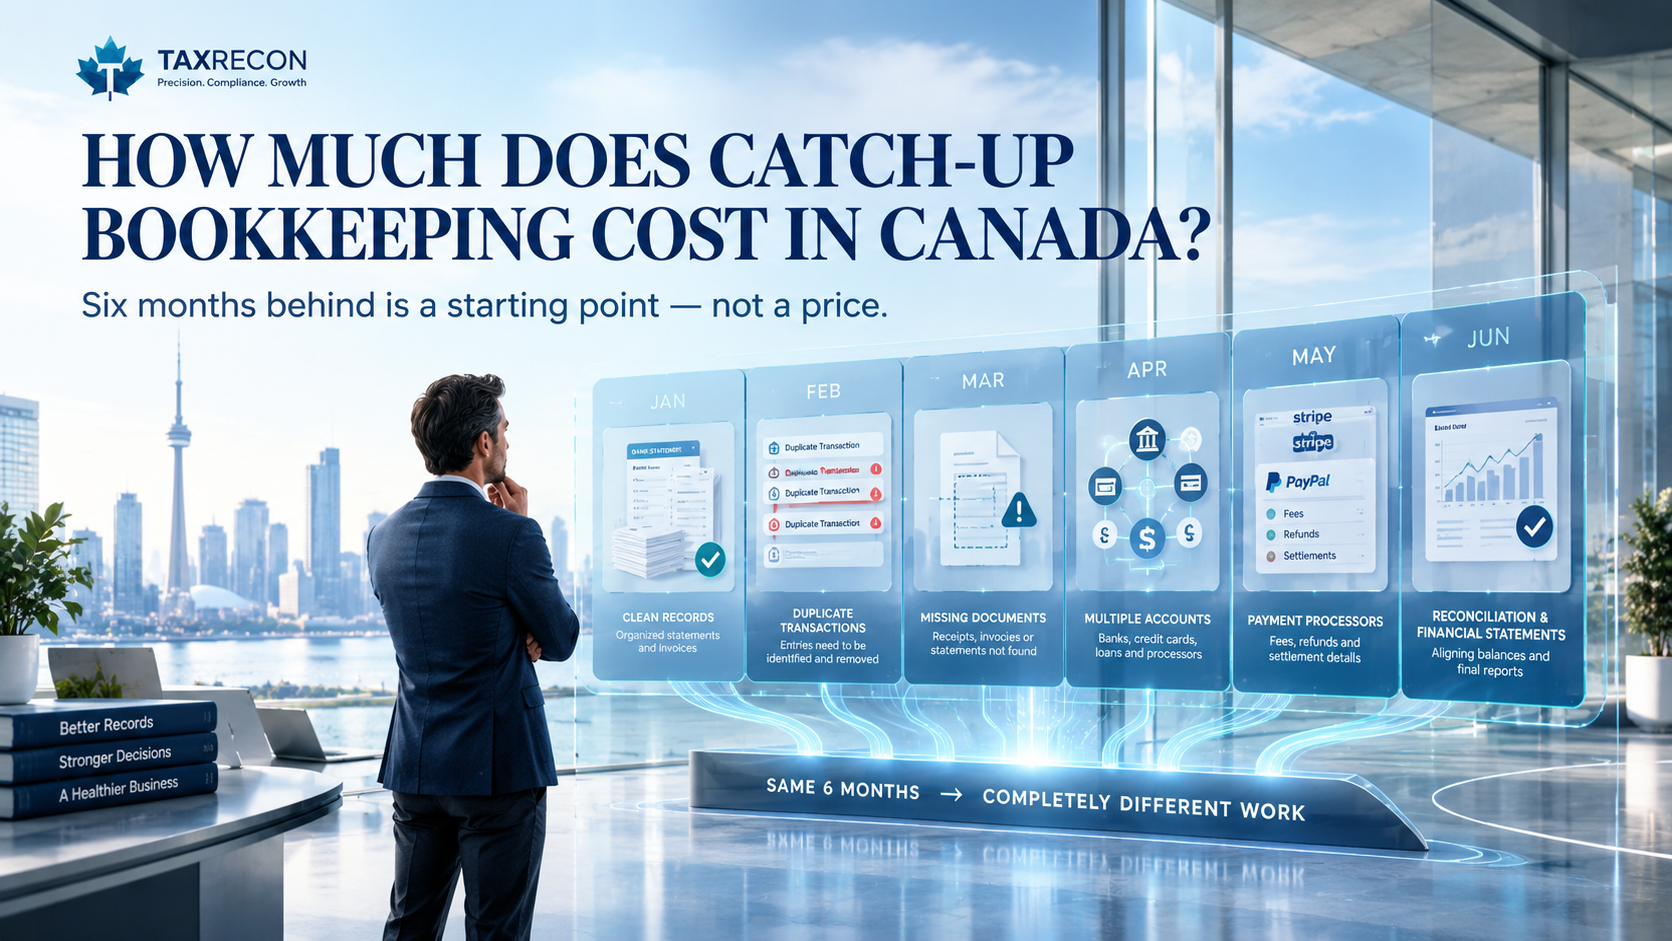
Six months behind is a starting point, not a price.
Published Canadian estimates put a six-to-twelve-month catch-up around C$1,500–C$5,000, but that range comes from one provider’s pricing guide, not a national fee survey. Your quote depends on the transactions to process, mistakes to correct, records to recover and accounts to reconcile.
The useful question is not simply, “How many months did I miss?”
It is “What needs to be done before I can trust the numbers again?”
TaxRecon approaches that question by separating historical bookkeeping from tax filings and other work that may depend on it.
Key Takeaways
- Months behind do not set the price. Transaction volume, account complexity and record condition determine the work.
- Catch-up, cleanup and reconstruction are different jobs. Your file may need more than one.
- Compare the same deliverables. Bookkeeping does not automatically include tax returns, software changes or CRA payments.
What can you reasonably budget?
Fluent Book’s May 2026 Canadian catch-up pricing guide publishes the following indicative ranges:
| Backlog described in the guide | Published project estimate, CAD |
| Three to six months | C$500–C$2,000 |
| Six to twelve months | C$1,500–C$5,000 |
| One to two years | C$3,000–C$10,000 |
| Three years or more | C$5,000–C$25,000+ |
These are that publisher’s estimates, not TaxRecon’s prices or independently measured Canadian averages. Use them to understand the possible scale of a project, then request a quote based on your own file.
The ranges overlap for a reason. Longer backlogs with complete statements and straightforward transactions can require less investigation than shorter periods containing duplicate entries, missing invoices and unexplained opening balances.
Do not compare a fee per overdue month with a fee for the entire project. Also separate the one-time historical project from the monthly bookkeeping you may need afterwards.
Before comparing prices, identify the work
Catch-up means the record is incomplete. Transactions from an earlier period still need to be entered, classified and reconciled.
Cleanup means entries exist, but something is wrong. The work may involve correcting categories, duplicates, transfers, reconciliation differences or balances carried forward incorrectly.
Reconstruction means the record must be rebuilt. Missing statements, inaccessible accounts or incomplete sales records can require additional evidence gathering before normal bookkeeping can begin.
These are practical scope descriptions, not interchangeable package names.
You could have current bank feeds and still need cleanup. You could have no accounting software and still have enough organized documents for a straightforward catch-up.
That distinction should appear in the quote.
What actually changes the price?
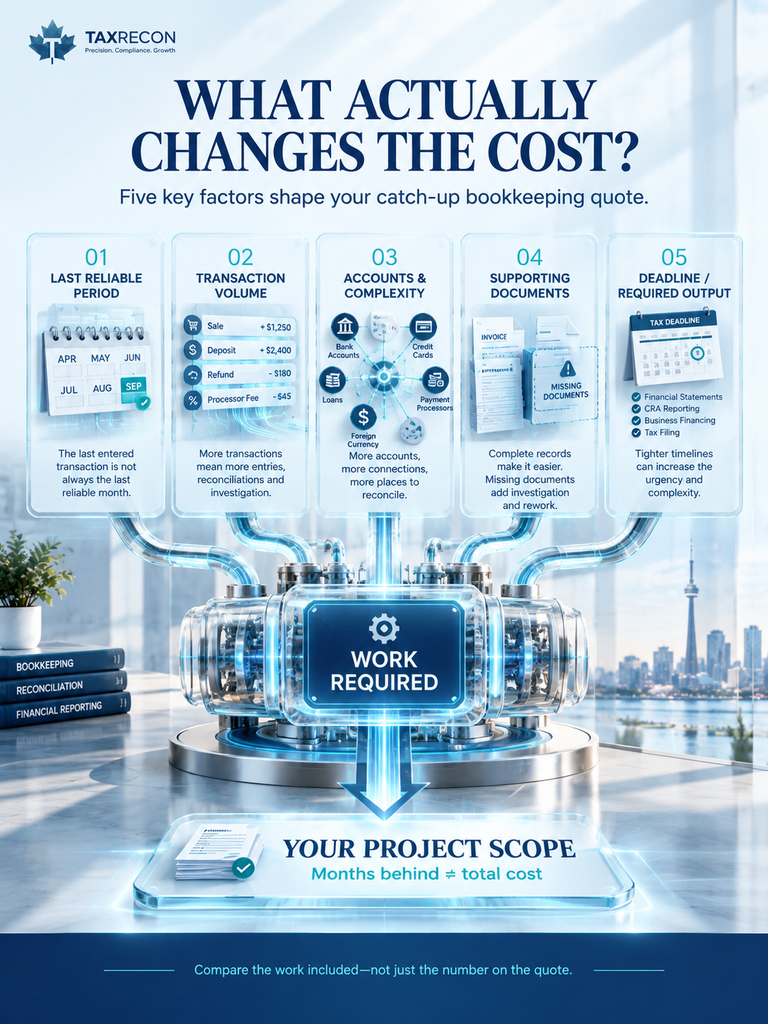
Where the last reliable period ends
The date of the last entered transaction is not necessarily the date the books were last correct.
Suppose September’s opening balance does not agree with August’s reconciliation. The bookkeeper may need to review earlier transactions before completing September.
Ask the provider to identify the starting point and explain how earlier problems will be handled if discovered.
How much activity sits behind each bank deposit
One deposit does not always represent one sale.
Online stores may receive a single payment-processor settlement covering many orders, refunds and fees. Recording only the net deposit may leave the sales and fee records incomplete.
Ask what “transaction volume” means in the quote: bank lines, invoices, individual orders or reconciled settlements.
Per-transaction pricing means little until you know what counts as a transaction.
How many accounts and accounting problems need attention
Bank accounts, credit cards, loans, payment processors and foreign-currency accounts each bring records that need to agree.
Unexplained transfers, owner-paid expenses, inventory and project tracking can add work beyond ordinary entry.
When an apparent mismatch is your main concern, start with TaxRecon’s guide to QuickBooks bank balances not matching the statement. It helps distinguish valid timing differences from errors that need correction.
Whether the supporting documents exist
Complete statements, invoices and settlement reports let the provider work from evidence.
Missing documents create questions: Was that transfer a loan, a customer payment or an owner contribution? Did the card payment cover a business purchase or personal spending?
Software cannot settle those questions simply by importing the transaction.
What has to happen after the bookkeeping
Tax filings, financing requests and business sales may determine the required delivery date and reporting detail.
Tell the provider about the deadline before the quote. Ask whether urgency changes the fee and what documents you must supply for the target date to remain realistic.
At TaxRecon, bookkeeping services include historical cleanup and reconciliation, while matters belonging to payroll, GST/HST or tax filing receive their own scope.
Same backlog, different job: an illustrative comparison
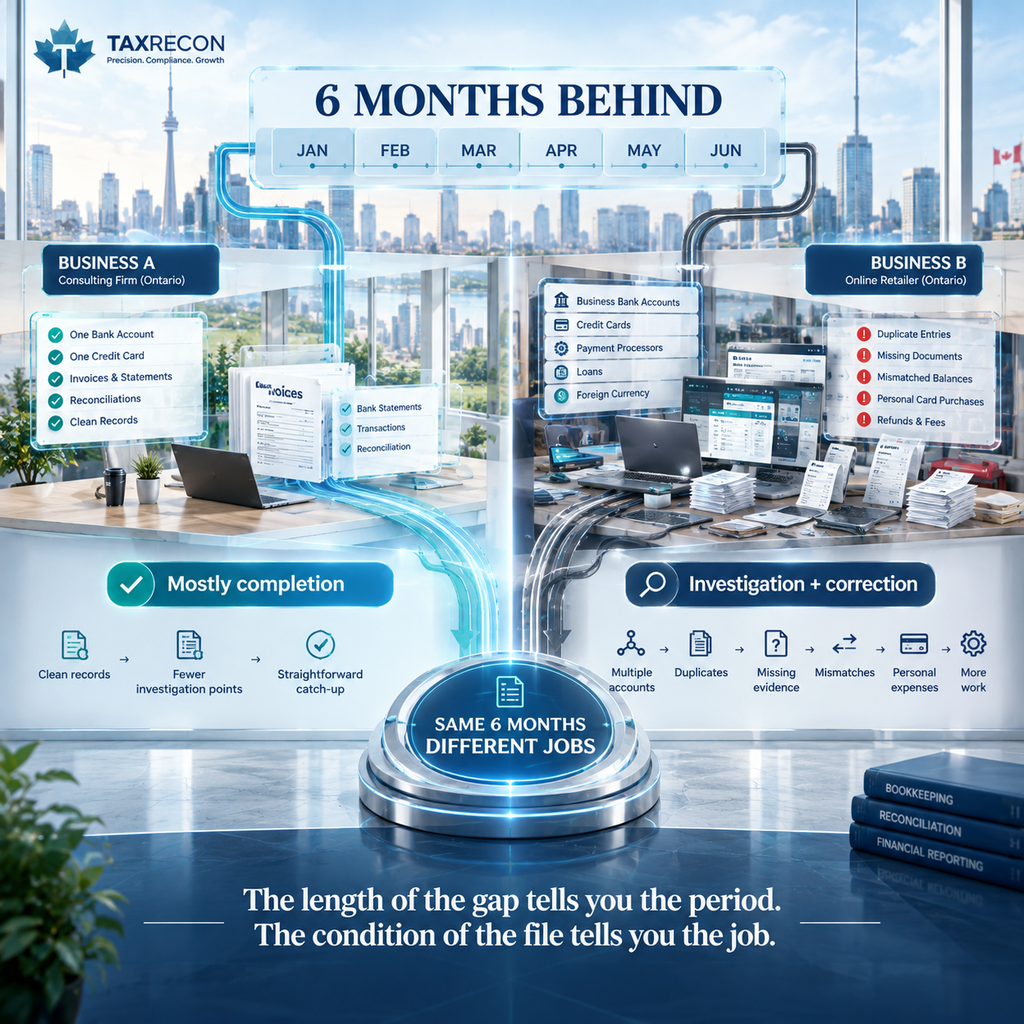
Picture two Ontario businesses, each six months behind.
The consultant has a business bank account, a credit card, clearly labelled invoices and complete statements. The earlier period reconciles. Most of the work involves recording the missing activity and matching the accounts.
The online retailer has several payment channels, refunds, settlement fees and transactions entered twice. Opening balances do not agree, and some purchases came through the owner’s personal card.
Both owners can accurately say, “I need six months caught up.”
They are not buying the same work.
The consultant mainly needs completion. The retailer also needs investigation and correction. These are illustrative situations, not TaxRecon client cases or price quotations.
The length of the gap tells you the period. The condition of the file tells you the job.
What should a complete catch-up quote include?
Compare quotes against the same finish line, not just the headline fee.
| Quote item | What to confirm before accepting |
| Initial review | Whether diagnosis is free, separately charged or credited against the project |
| Period covered | Exact start and end dates, including treatment of opening balances |
| Accounts included | Named bank, card, loan and processor accounts |
| Historical entry and corrections | Whether missing activity, duplicates and misclassifications are covered |
| Reconciliation | Which accounts will be reconciled, through which date |
| Handover | Reports, adjustment notes and a list of unresolved questions |
| Separate work | Tax filings, payroll corrections, software migration and ongoing bookkeeping |
| Price changes | What can trigger extra charges and how you approve them |
“Clean books” needs a practical definition.
Request an income statement and balance sheet for the agreed period, supporting reconciliations and a clear explanation of anything still outstanding.
Balances should not become “correct” merely because someone posts an unexplained adjustment. Equally, a legitimate outstanding payment does not need to disappear just to make a report look tidy.
Keep the bookkeeping bill separate from the tax bill
Correcting historical accounts does not itself submit an overdue return or pay a CRA balance.
TaxRecon’s tax filing services cover personal, self-employed and corporate returns, including outstanding years. Confirm whether that work is part of the engagement or separately quoted.
For incorporated businesses, the guide to T2 corporate tax returns in Canada explains how the accounting records feed into the return.
Budget separately for professional fees, software or document-retrieval costs, applicable sales tax and any amounts payable to CRA.
Is fixed-fee or hourly pricing better?
Neither label makes a quote fair by itself.
Fixed-fee pricing gives you a defined project price when the provider can assess the work. Check the assumptions, exclusions and approval process for additional work. “Fixed” should refer to a written scope, not an unlimited promise.
Hourly pricing can suit a targeted investigation when the cause of a problem is unknown. Ask for an initial estimate, a spending limit and a review point before more time is billed.
Per-month or transaction-based pricing can help describe the backlog, but confirm how corrections and unusually complex periods affect the total.
Your protection is not the billing label. It is knowing what you are buying and when permission is needed to increase the bill.
How to reduce the cost without creating more cleanup
Watching the budget is reasonable. Statistics Canada’s August 31, 2026 business survey found that 59.8% of Canadian employer businesses expected cost-related obstacles over the following three months.
The practical response is to reduce avoidable searching and uncertainty, not hide work that will surface later.
- Collect the full period. Provide complete bank and credit-card statements, including closed accounts, rather than selected screenshots.
- Identify the starting point. Supply the last reconciliation and prior year-end reports available. Flag anything you do not trust.
- Group supporting records. Organize sales invoices, purchase documents, payroll records and merchant settlements by period and account.
- Name one contact for questions. Consolidated answers reduce conflicting instructions and repeated follow-up.
- Preserve the existing file. Ask before deleting entries, undoing reconciliations or moving software. Changes made to “tidy up” can remove useful history.
Use the provider’s approved document-sharing process and appropriate accountant access. Do not email banking passwords.
Three shortcuts that can make a cheap quote expensive
“The bank feed already has everything.”
Imported activity is not the same as reviewed, classified and reconciled bookkeeping. Ask which checks the provider will complete.
“We will start fresh and ignore the old balance.”
The new monthly process still needs a defensible starting position. Historical cleanup and current work may run in parallel, but their boundaries should be explicit.
“The catch-up will pay for itself in tax savings.”
Better records can support a more accurate return. They do not guarantee a refund, new deductions or savings larger than the fee.
Do this: buy a documented result for a defined period.
Not that: choose the lowest number and assume the missing work is included.
Final thoughts: buy a clear finish line
Catch-up bookkeeping cost in Canada depends on the work required to make a historical period usable again, not simply the number of months on a calendar.
Use published ranges to plan. Use a file review to establish the price. Then compare quotes by their periods, accounts, corrections, deliverables and exclusions.
The most useful quote answers this question: “What will be reliable when the work is finished, and what will still need attention?”
Bring the records you have to TaxRecon and request a catch-up bookkeeping review. Start with the last period you trust, the deadline ahead and the questions you need the books to answer.
Questions owners ask before approving a catch-up project
How much does TaxRecon charge for catch-up bookkeeping?
TaxRecon does not publish a universal catch-up price. Its bookkeeping page says the quote depends on file condition, complexity, transaction volume, accounts and reconciliation needs. Start with a records review rather than treating another provider’s published range as TaxRecon’s fee schedule.
How long does catch-up bookkeeping take?
The timeline depends on the backlog, correction work and availability of documents and answers. Ask for milestones tied to the agreed scope. Confirm when work can start, what must be supplied first and how unresolved questions affect the completion date.
Can work begin if some receipts are missing?
Yes, the review can begin with the records available. Identify the gaps openly and retrieve replacement invoices where possible. Bank activity may help reconstruct transactions, but it does not answer every question about their purpose or tax treatment. Do not invent missing details.
Can monthly bookkeeping start while the backlog is being corrected?
Yes, where the provider agrees to separate current work from historical correction. Confirm the starting balances, reporting limitations and who owns each period. Otherwise, new reports may continue to carry unresolved differences from the backlog.
Is catch-up bookkeeping tax-deductible?
Business-related accounting fees may qualify. The CRA’s professional-fee guidance for self-employed businesses states:
“You can deduct accounting and legal fees you incur to get advice and help with keeping your records.”
Ask your preparer to confirm the treatment and reporting year for your circumstances, particularly when an invoice covers work on several earlier years.
Should I expect to pay everything upfront?
Payment terms vary by provider and project. Ask whether payment is a deposit, a milestone amount or the full fee. The agreement should explain the work covered, cancellation terms and what happens if missing information prevents completion. No single payment structure is a universal Canadian rule.
Do corrected books mean I must amend earlier tax returns?
Not automatically. Ask the tax preparer whether the corrections change figures already filed. Bookkeeping adjustments and tax-return amendments are separate decisions. Keep an explanation of the correction and identify which years or filings may be affected.
Can TaxRecon work with my existing QuickBooks or Xero file?
Yes. TaxRecon’s bookkeeping scope includes QuickBooks and Xero support. The review should establish whether the existing file needs routine catch-up, corrections or a larger systems project. Do not assume you need new software simply because the current books are behind.