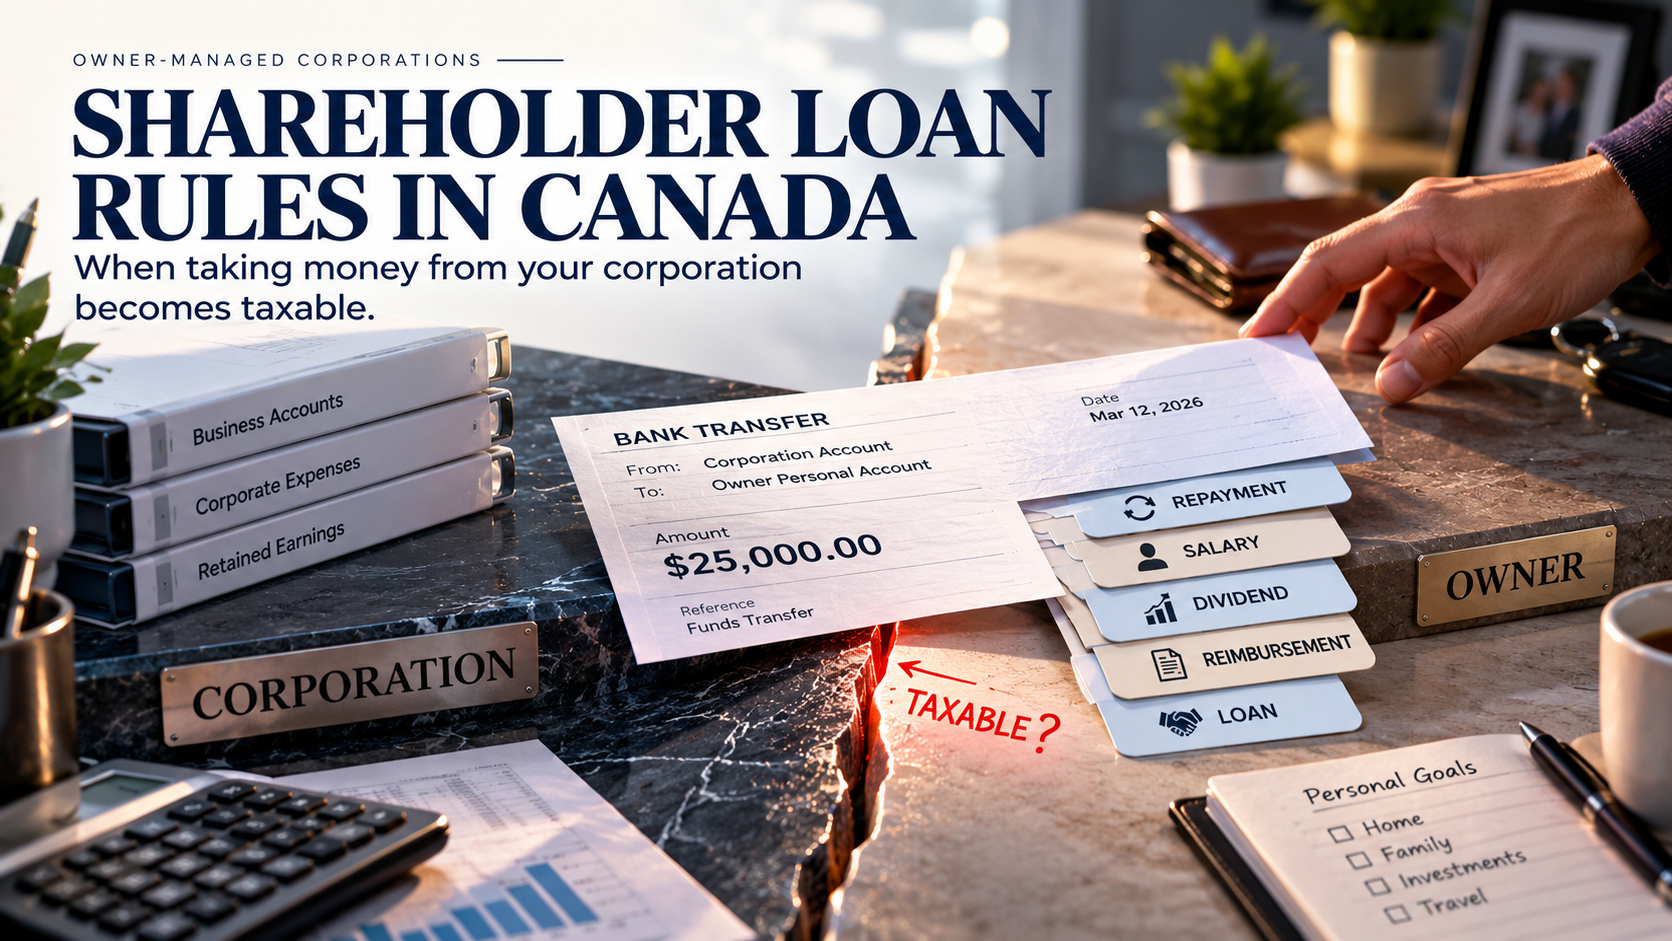
Money leaves your corporation and lands in your personal bank account. Maybe you need it for a home expense, a credit-card payment, or simply want access to cash the business has built up.
The transfer itself does not tell you how CRA will tax it.
If the corporation did not already owe you that money, and the withdrawal was not properly treated as salary, a dividend, reimbursement, or another valid payment, it may create a shareholder loan. That can be perfectly manageable for a period of time. Leave the balance unresolved, however, and the amount can become taxable personally.
For Canadian owner-managed corporations, getting the shareholder loan account right matters because it connects bookkeeping, corporate tax, personal tax, compensation planning, and CRA compliance.
TaxRecon helps Canadian businesses connect those records rather than looking at each transaction in isolation.
Key Takeaways
- Money you take from your corporation is not automatically salary, a dividend, or tax-free cash.
- The tax result changes depending on whether you owe the corporation or the corporation owes you.
- CRA’s repayment exception is generally tied to the corporation’s tax year, not simply 12 months from the withdrawal date.
- Repaying a loan temporarily and borrowing substantially the same money again can create a problem under CRA’s series-of-loans rules.
- Even when the full loan is not included in income, an interest-free or low-interest balance can create a separate taxable interest benefit.
What Is a Shareholder Loan in Canada?
A shareholder loan records money moving between a corporation and its shareholder when the amount represents a genuine debt rather than salary, a dividend, reimbursement, or another type of payment.
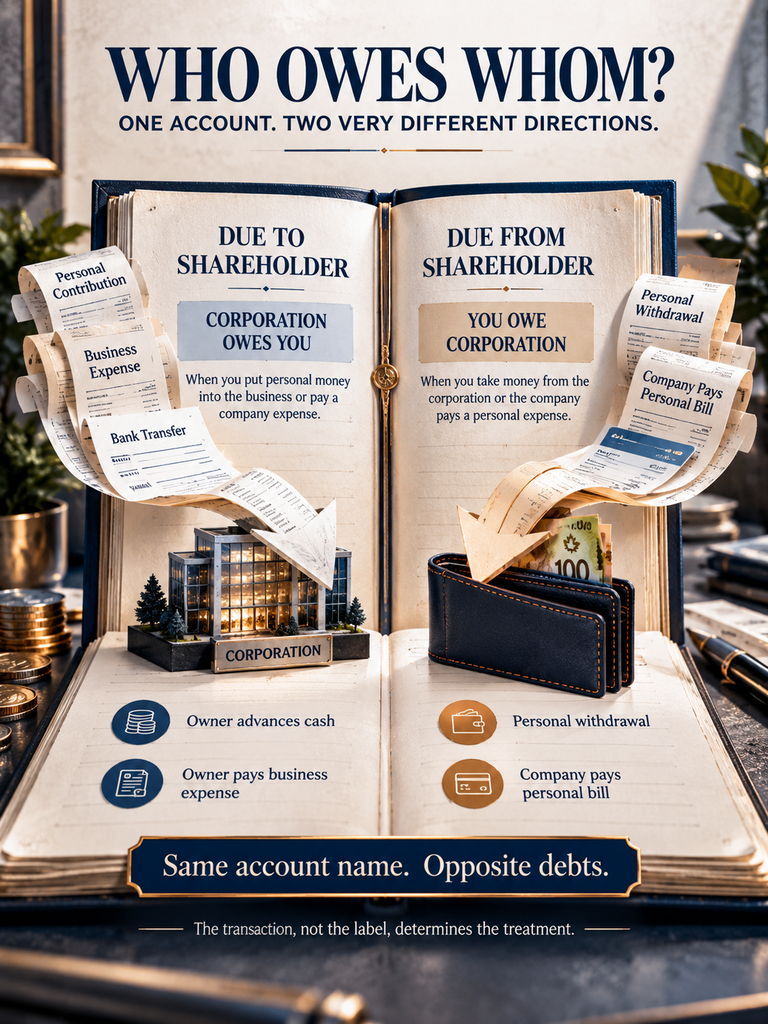
The account can move in either direction.
If you put personal money into the corporation, pay a company bill personally, or leave money in the company that it owes back to you, the corporation may owe you.
If you withdraw corporate cash for personal use, have the company pay personal expenses, or otherwise receive money that you are expected to repay, you may owe the corporation.
That distinction sounds simple, but it is where many bookkeeping problems begin.
| Situation | Typical Account Position | Who Owes Whom? | Main Tax Concern |
| You pay a business expense personally | Due to shareholder | Corporation owes you | Correctly record the expense and amount owing |
| You contribute personal cash to the business | Due to shareholder | Corporation owes you | Support the contribution and track repayment |
| You withdraw corporate cash for personal use | Due from shareholder | You owe corporation | Possible subsection 15(2) income inclusion |
| Corporation pays your personal bill | Often due from shareholder if a genuine debt exists | You owe corporation | Loan or shareholder-benefit treatment must be reviewed |
| Corporation repays money it genuinely owes you | Reduction of due-to-shareholder balance | Debt to you falls | Usually different from salary or dividend income |
The account is therefore not simply a place to park unexplained transfers.
CRA’s current shareholder-loan folio says accounting entries do not decide the substance of a transaction. The agency puts it plainly: “tax consequences arise from what taxpayers have actually done.” Read CRA Income Tax Folio S3-F1-C1
That principle matters.
Calling a personal withdrawal a “loan” in QuickBooks does not automatically make it a valid loan for tax purposes.
When Can Taking Money From Your Corporation Become Taxable?
When a shareholder receives a loan or incurs a debt because of shareholding, subsection 15(2) of Canada’s Income Tax Act can generally require the amount to be included in the borrower’s income unless an exception applies.
For a typical owner-manager, the risk often starts with an ordinary transfer.
You move money from the corporate bank account to your personal account.
Nothing was run through payroll.
No dividend was declared.
The corporation did not already owe you that amount.
No business expense was being reimbursed.
The books then show a growing debit balance in the shareholder loan account.
That balance deserves attention before year-end planning turns into a tax correction.
The key question is not just “Did I take money?”
Ask:
What was the corporation legally and economically paying me for?
Possible answers include:
- repayment of money the corporation already owed you
- salary or bonus
- dividend
- reimbursement of a supported business expense
- shareholder loan
- another shareholder benefit
Those categories produce different accounting and tax results.
This is why clean records matter. TaxRecon’s bookkeeping services focus on reconciliations, transaction classification, owner activity, and balances that need explanation before they flow into another accounting responsibility.
The “One-Year Rule” Does Not Mean One Year From the Withdrawal Date
This is one of the most important shareholder loan Canada rules to understand correctly.
CRA’s subsection 15(2.6) guidance generally provides an exception where:
- the loan is repaid within one year after the end of the lender corporation’s tax year in which the loan was made, and
- the repayment is not part of a series of loans or other transactions and repayments. See CRA’s current shareholder-loan repayment rules
That is different from counting 365 days from the date you withdrew the money.
Illustrative Example
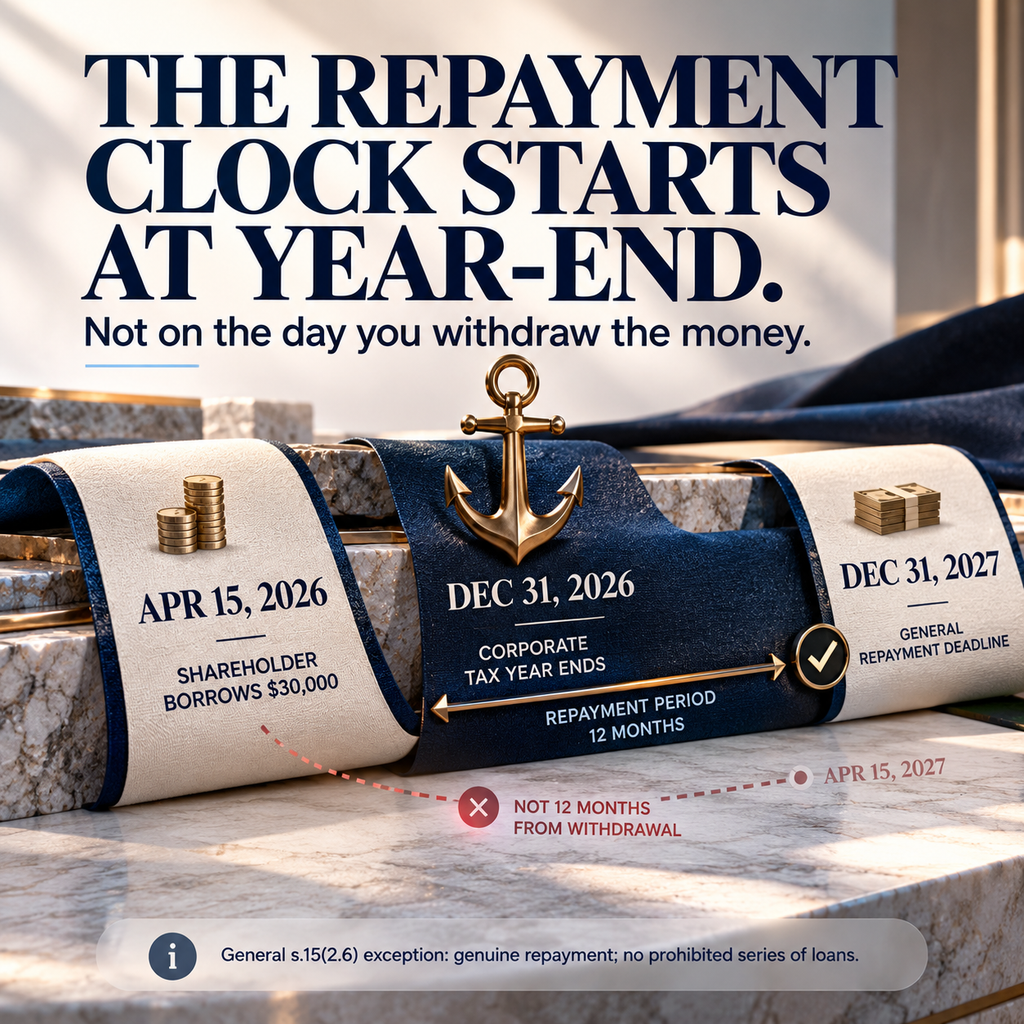
Suppose your corporation has a December 31 year-end.
You withdraw $30,000 on April 15, 2026 and the amount becomes a genuine shareholder loan.
The corporation’s tax year in which the loan arose ends December 31, 2026.
Under the general subsection 15(2.6) timing test, repayment would need to occur by December 31, 2027, assuming the other conditions are met and the repayment is not part of a prohibited series.
Now suppose you borrowed the money on December 20, 2026 instead.
The general deadline would still relate to the end of the following corporate tax year, not December 20, 2027.
That is why shareholder-loan deadlines should be tracked from the corporation’s year-end rather than through a simple “12 months from withdrawal” reminder.
What Happens If You Miss the Repayment Window?
Missing the applicable repayment test can move the issue back to the year when you originally received the loan.
CRA explains that when subsection 15(2.6) was expected to apply but ultimately does not, the borrower may need to amend the return for the year in which the loan arose and include the amount in income. Additional tax and interest can then follow.
That timing catches business owners off guard.
You could discover the problem in 2027 or later but have to correct an earlier personal tax year.
Later repayment does not simply erase the original problem
There is an important second rule.
If an amount was already included in your income under subsection 15(2) and you later genuinely repay all or part of the loan, paragraph 20(1)(j) can generally provide a deduction in the year of repayment, assuming the repayment is not part of a series of loans or other transactions and repayments.
So the sequence can look like this:
Year 1: loan arises
Later deadline: repayment exception is missed
Year 1 return: amount becomes taxable under subsection 15(2)
Later year: genuine repayment occurs
Later-year return: a deduction may become available
That is very different from pretending the original income inclusion never existed.
Why Repaying the Loan and Borrowing It Again Can Fail
One of the weakest strategies is to clear the shareholder loan just before the deadline and then take substantially the same money back shortly afterwards.
CRA specifically addresses a series of loans or other transactions and repayments.
The purpose of the rule is to prevent taxpayers from continually postponing income inclusion by using new advances to repay older ones. CRA looks at the facts rather than only the dates entered in the ledger.
Do This, Not That
Do this:
Make a genuine repayment that changes your financial position and keep evidence showing what happened.
Not that:
Borrow short-term money to clear the shareholder balance, then take essentially the same amount back from the corporation shortly afterwards simply to reset the clock.
CRA’s current guidance contains an example involving exactly this type of temporary repayment and re-borrowing pattern.
Can Salary or a Dividend Clear a Shareholder Loan?
Salary, bonuses, and dividends can sometimes be applied against an amount the shareholder owes the corporation.
The tax treatment does not disappear. It changes.
CRA’s current folio says repayments resulting from applying dividends, salaries, or bonuses owed to the borrower are not considered part of a series of loans and repayments for this purpose.
If a salary or bonus is used
The amount becomes employment income to the shareholder.
The corporation may generally receive the related deduction when the payment meets the applicable tax rules, and payroll responsibilities can arise.
If a dividend is used
The corporation can declare a dividend payable to the shareholder and apply that payable amount against the shareholder loan.
The shareholder still reports the dividend under the applicable dividend rules.
The dividend does not become tax-free simply because cash did not physically move into the shareholder’s bank account.
If you are deciding whether future owner compensation should come through payroll, dividends, or a combination, TaxRecon’s guide to salary vs dividends in Ontario explains how the two payment methods affect the corporation and owner differently.
Does a Shareholder Loan Have to Charge Interest?
Not every shareholder-loan issue ends with subsection 15(2).
A separate rule can matter when a shareholder receives an interest-free or low-interest loan.
Where the full loan is not included in income under subsection 15(2), subsection 80.4(2) can create a deemed interest benefit on a qualifying shareholder loan. CRA calculates that benefit using the applicable prescribed rate, reduced by qualifying interest actually paid within the permitted period. Read CRA’s deemed interest benefit guidance
Current 2026 Rate
For October 1 through December 31, 2026, CRA’s prescribed annual rate used to calculate taxable benefits for employees and shareholders from interest-free and low-interest loans is 3%. See CRA’s fourth-quarter 2026 prescribed rates
That rate can change quarterly.
Do not assume that meeting the subsection 15(2.6) repayment deadline automatically means there is no other tax consequence during the period the loan remained outstanding.
This is one area where a short-term shareholder loan can still require year-end tax work even if the principal is eventually repaid in time.
What Does “Due to Shareholder” vs “Due From Shareholder” Mean?
These labels tell you which direction the debt runs.
Due to shareholder
The corporation owes money to the shareholder.
This can happen when you:
- put personal cash into the corporation
- pay a legitimate company expense personally
- advance funds to cover operating costs
- leave a supported amount in the business that remains payable to you
When the corporation later repays a genuine amount it already owes you, that repayment is fundamentally different from taking new corporate income for personal use.
Due from shareholder
The shareholder owes money to the corporation.
This can arise when you:
- transfer corporate cash to yourself without another valid classification
- use a corporate card for a personal purchase
- have the corporation pay a personal bill
- take repeated owner draws without salary or dividend treatment
A due-from-shareholder balance is the side that normally deserves closer attention under subsection 15(2).
What Most Business Owners Get Wrong
“It is my corporation, so the cash is mine”
The corporation is a separate taxpayer.
Ownership of the shares does not make every dollar in the corporate bank account personal money that can be removed without a tax result.
“My bookkeeper called it a shareholder loan, so CRA has to accept it”
No.
CRA says the substance of the transaction matters more than the accounting entry alone.
Documentation, actual cash movement, the reason for the transaction, repayment behaviour, and the relationship between the parties all matter.
“I have one year from the day I took the money”
Not necessarily.
The common repayment exception generally looks to one year after the end of the corporation’s tax year in which the loan arose.
“I can repay it on December 30 and borrow it back in January”
That can run directly into the series-of-loans rule.
“If I miss the deadline, I can fix the bookkeeping entry”
Changing the account name does not change what actually happened.
If the tax rule already requires income inclusion, the issue may require a tax-return correction rather than a cosmetic journal entry.
“No interest means no problem”
Not necessarily.
Even when subsection 15(2) does not include the principal in income, subsection 80.4 may create a separate deemed interest benefit.
Use the Five-Question Shareholder Loan Check
Before you take money from the corporation, or before year-end closes, ask five questions.
1. Why did the money move?
Was it:
- personal borrowing
- reimbursement
- salary
- dividend
- repayment of money the corporation owed you
- payment of a personal cost by the company
Start with the real transaction, not the account name.
2. Who owes whom after the transaction?
Check whether the shareholder loan account is:
- due to the shareholder
- due from the shareholder
That single distinction changes the direction of the tax review.
3. When did the balance arise?
Record the actual dates and connect them to the corporation’s fiscal year.
Without the timing, you cannot reliably assess the subsection 15(2.6) repayment window.
4. Has there been a genuine repayment?
Look for real evidence:
- bank transfer
- properly applied salary
- properly declared dividend
- other valid set-off
- transfer of property where appropriate
Do not rely only on a year-end journal entry.
5. What still needs to be reported?
Depending on the facts, the transaction may affect:
- the corporation’s bookkeeping
- corporate tax records
- the shareholder’s personal income tax
- payroll
- dividend reporting
- deemed interest benefits
That is why shareholder loans should be reviewed as part of the broader financial record rather than after the T2 is already being finalised.
Practical Steps If Your Shareholder Loan Balance Already Looks Wrong
Step 1: Pull the shareholder loan ledger
Review every debit and credit making up the current balance.
Do not work only from the final total.
Step 2: Match each transaction to evidence
Use:
- corporate bank statements
- personal bank records where relevant
- receipts
- invoices
- expense claims
- payroll records
- dividend resolutions
- prior-year financial statements
Step 3: Separate business expenses from personal withdrawals
A business expense paid personally should not remain mixed with money you borrowed for personal use.
Likewise, a corporate payment of a personal expense should not stay hidden inside an operating expense account.
If the books contain several owner-account errors, TaxRecon’s bookkeeping cleanup guide explains why owner transactions and shareholder balances need to be traced back to supporting records before reports can be trusted.
Step 4: Identify the corporate year in which each loan arose
This establishes the timing needed for the repayment analysis.
Running shareholder loan accounts can contain advances from several periods, so one current balance may actually contain amounts with different tax histories.
Step 5: Review repayment and compensation options before posting adjustments
Depending on the facts, the next step may involve:
- cash repayment
- salary or bonus
- dividend
- correcting a misclassified business expense
- amending an earlier personal return
- recognising a deemed interest benefit
Do not choose the journal entry first and build the explanation afterwards.
Illustrative Scenario: When One Balance Contains Three Different Transactions
Consider an incorporated Ontario consultant with a December 31 year-end.
During 2026:
- the shareholder transfers $20,000 from the corporate account to a personal account
- the shareholder personally pays a $4,000 business software invoice
- the corporation pays a $2,500 personal credit-card bill
A rushed bookkeeping process could place all three amounts in one owner account and leave only a net balance.
That hides what actually happened.
The $4,000 business expense paid personally can create an amount the corporation owes the shareholder, assuming the expense is valid and properly supported.
The $20,000 personal transfer can create an amount the shareholder owes the corporation.
The $2,500 personal credit-card payment also needs to be analysed based on whether a genuine shareholder debt was created or another shareholder-benefit rule applies.
Netting everything together without reviewing the underlying transactions can hide the tax exposure.
This is why the ledger matters more than the final balance.
How Shareholder Loans Connect to Your Corporate Tax Return
Shareholder-loan balances often become visible during year-end bookkeeping and corporate tax preparation.
That is the wrong time to discover that a large personal balance has been accumulating without anyone tracking when it arose.
Before completing a corporate return, review:
- the opening shareholder balance
- every owner withdrawal
- personal expenses paid through the corporation
- business costs paid personally
- repayments during the year
- declared dividends
- salary and bonuses
- prior-year shareholder balances
- any amounts previously included in personal income
- interest treatment where relevant
TaxRecon’s tax filing services include T2 corporate tax preparation based on the records behind the return, which matters when shareholder activity affects both the corporation and its owner.
When Professional Review Makes Sense
Consider getting the account reviewed before filing if:
- the corporation has paid personal expenses
- you regularly transfer money between corporate and personal accounts
- the balance has carried forward for more than one fiscal year
- you do not know whether the account is due to or due from shareholder
- the balance changed significantly near year-end
- you repaid money and borrowed again shortly afterwards
- salary or dividends may be used to clear the balance
- prior tax returns may have treated the balance incorrectly
- your bookkeeping contains old owner transactions that no longer make sense
- a shareholder is non-resident or the structure involves related corporations
Special statutory exceptions can apply in some situations, including certain shareholder-employee loans and loans made in the ordinary course of a money-lending business. Those rules contain conditions that go beyond the standard owner-manager example, so they should be reviewed on their own facts.
Final Thoughts
Taking money from your corporation is not automatically a tax problem.
The problem begins when nobody can clearly explain why the money moved, who owes whom, when the debt arose, and how the balance will be dealt with.
For most incorporated business owners, the safest approach is to review the shareholder loan account throughout the year rather than waiting until the corporate return is ready to file.
Keep the transactions supported. Track the corporation’s year-end. Treat repayments as real transactions. Separate salary, dividends, reimbursements, owner contributions, and personal withdrawals instead of allowing them to collect inside one unexplained balance.
When a shareholder loan Canada issue already exists, start with the ledger and the facts behind it. Once those are clear, you can determine whether the next step belongs in bookkeeping, personal tax, corporate tax, payroll, or a combination of them.
Need Help Reviewing a Shareholder Loan Balance?
If your shareholder loan account contains old withdrawals, personal expenses, unexplained entries, or a balance you are not sure how to clear, TaxRecon can review the records before the issue carries into another filing period.
Start with the transaction history, supporting records, and corporate year-end. From there, the accounting and tax treatment can be assessed based on what actually happened.
Frequently Asked Questions
What is a shareholder loan in Canada?
A shareholder loan records a genuine debt between a corporation and its shareholder. It can represent money the shareholder lent to the company or money the shareholder borrowed from it. The tax concern becomes more serious when the shareholder owes the corporation and the balance remains outstanding.
Can I borrow money from my corporation without paying tax?
Possibly for a limited period, but you cannot assume every corporate withdrawal is tax-free. Subsection 15(2) can include a shareholder loan in income unless an applicable exception applies. The repayment timing, purpose of the loan, documentation, and any repeat borrowing all matter.
Is the shareholder loan deadline one year from the day I borrowed the money?
No. The commonly used “one-year rule” is more specific. The subsection 15(2.6) exception generally requires repayment within one year after the end of the corporation’s tax year in which the loan was made, provided the repayment is not part of a series of loans or transactions.
Can a dividend repay a shareholder loan?
Yes, a properly declared dividend payable to the shareholder can be applied against an outstanding shareholder loan. The dividend itself remains taxable to the shareholder under the dividend rules. CRA states that this type of repayment is not treated as part of a series of loans and repayments for subsection 15(2.6).
Can salary be used to clear a shareholder loan?
Yes, salary or a bonus owed to the shareholder can be applied against a shareholder-loan balance when handled correctly. The salary or bonus remains employment income and can bring payroll withholding and reporting responsibilities. It should not be created only as an unsupported year-end bookkeeping label.
What happens if I repay a shareholder loan after it was already taxed?
A later genuine repayment can generally create a deduction under paragraph 20(1)(j) in the year you repay the amount that was previously included in income. The repayment must not form part of a prohibited series of loans or other transactions and repayments.
Does an interest-free shareholder loan create taxable income?
It can create a separate deemed interest benefit even when the principal is not included under subsection 15(2). CRA uses prescribed interest rates to calculate the benefit under subsection 80.4, subject to the detailed rules and qualifying interest actually paid within the permitted period.
Can my corporation repay money it owes me without calling it salary or a dividend?
Yes, when the corporation genuinely owes you money, repaying that existing debt is different from paying new salary or declaring a dividend. The underlying contribution or business expense should be properly supported so the repayment can be traced to a real amount due to you.
Should I review my shareholder loan before filing the T2?
Yes. Reviewing it before the T2 is prepared gives you time to identify personal withdrawals, owner-paid business expenses, repayments, dividends, payroll entries, and older balances. Waiting until the return is almost finished can leave less time to correct records or assess personal-tax consequences.