Choosing the wrong year-end will not ruin your corporation, but it can make every future year more awkward than it needs to be.
New Canadian corporations have flexibility when setting their first fiscal year-end. That does not mean the best choice is automatically December 31, the last possible date, or whatever month your incorporation happened to fall in.
Your corporate year end Canada decision affects when your books close, when your T2 is filed, when corporate tax may become payable, when year-end planning happens, and how easily your accounting calendar fits the way your business actually operates.
For business owners who want their bookkeeping, tax filing, and planning to work together, TaxRecon looks at the year-end as part of the wider financial picture rather than as an isolated date.
Short Answer: What Year-End Should a New Corporation Choose?
Pick a fiscal year-end that gives your first corporation enough operating time, falls outside your busiest business period where possible, and creates a practical annual accounting cycle.
CRA generally allows a new corporation to choose its first year-end within 53 weeks, or 371 days, of incorporation. Once that year-end is established, changing it later normally requires CRA approval.
Key Takeaways
- Your first corporate tax year generally cannot exceed 53 weeks or 371 days.
- December 31 can be convenient, but it is not automatically the strongest choice.
- A year-end shortly after incorporation can create an unnecessarily short first reporting period.
- A date shortly after your busy season can make bookkeeping, inventory counts, receivable reviews, and tax planning easier.
- Your T2 filing deadline is generally six months after year-end, while corporate tax may be payable earlier.
- Once the date becomes established, CRA normally expects the corporation to keep the same fiscal period.
What Does a Corporate Year-End Actually Mean?
Your corporate year-end is the final day of your corporation’s tax year.
For corporations, CRA treats the tax year as the fiscal period.
Suppose your corporation uses September 30 as its year-end.
Its regular fiscal year would usually run:
October 1 to September 30
The company closes its books on September 30, prepares its year-end financial information based on that period, calculates corporate income tax for that period, and files its T2 based on those dates.
This is different from an individual’s tax year.
Individuals normally report income using the January 1 to December 31 calendar year. Most corporations have more flexibility.
Current CRA Rule
CRA currently states that a corporation’s fiscal period cannot be longer than 53 weeks, or 371 days. A newly incorporated company can generally choose any first tax year-end within that limit.
That number matters because it defines your available window.
It does not tell you which date inside that window is right for your business.
How Do You Choose the Best First Corporate Year-End?
Instead of beginning with a month, begin with five questions.
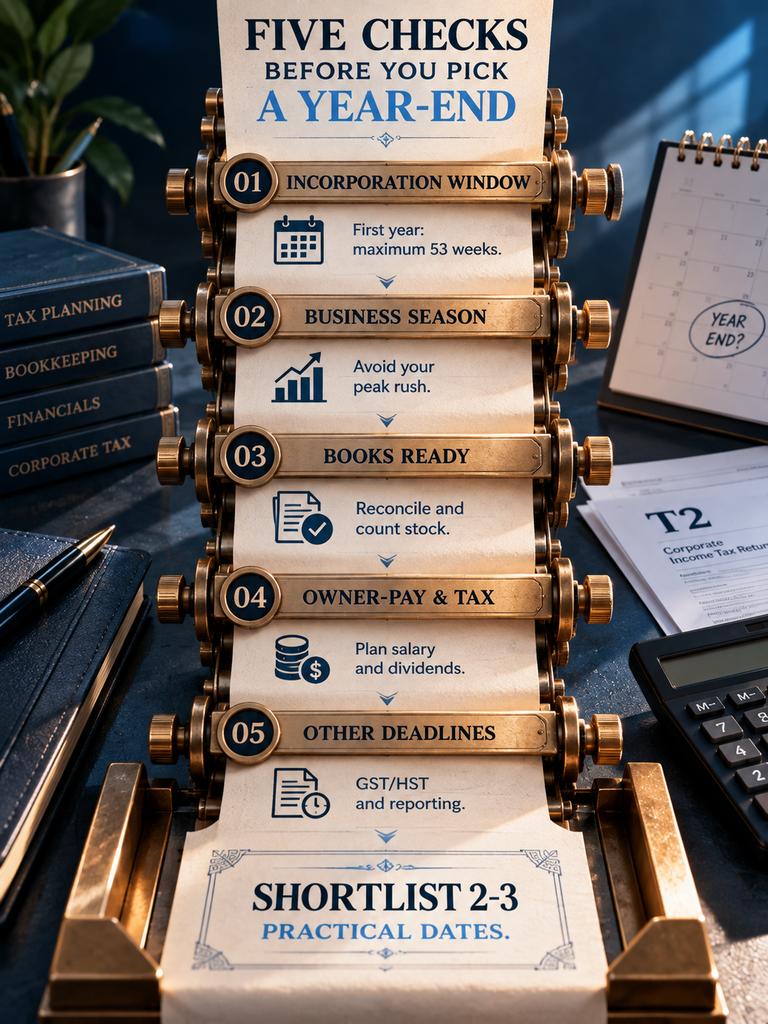
1. When Did You Incorporate?
Your incorporation date sets the starting point.
Your first corporate tax year begins on the incorporation date, and the first year-end must fall within the permitted 53-week period.
This means two businesses incorporated on different dates may reach very different answers even if their operations are otherwise similar.
Imagine incorporating on October 15, 2026.
You might consider:
- December 31, 2026
- March 31, 2027
- June 30, 2027
- September 30, 2027
All create very different first reporting periods.
Choosing December 31 would create a very short first corporate year.
Choosing September 30, 2027 would give the business almost a full year of operations before its first year-end.
Longer is not always better, but an unnecessarily short first year can bring accounting and filing work forward before the business has had much time to operate.
2. When Is Your Business Least Busy?
This may be the most practical question.
Year-end normally creates extra work:
- bank and credit-card reconciliations
- reviewing accounts receivable
- confirming accounts payable
- checking shareholder transactions
- reviewing payroll balances
- checking GST/HST accounts
- identifying assets purchased or sold
- reviewing unusual expenses
- completing financial statements
- tax planning
- preparing the T2
Doing all of this during your busiest month can create unnecessary pressure.
A landscaping company that earns most of its revenue from April through October may find an October 31 or November 30 year-end more practical than June 30.
A retailer with a major December holiday season may prefer not to close its fiscal year while sales, inventory, staffing, and returns are at their busiest.
The goal is not to find the quietest possible day.
Pick a period when the records can realistically be closed and reviewed.
3. When Will Your Books Be Easiest to Close?
Business seasonality and accounting workload are related, but they are not identical.
Think about what sits on your balance sheet at different points in the year.
For example:
- Is inventory unusually high in December?
- Are customer receivables highest in March?
- Do large supplier bills arrive after a seasonal rush?
- Does your business carry large deposits at certain times?
- Does one month generate unusually high payroll?
- Are projects normally completed at a particular point in the year?
A cleaner operational point can make the year-end numbers easier to understand.
That matters because your T2 is built from those financial records.
TaxRecon’s Tax Filing Services include T2 corporate return preparation based on the corporation’s applicable tax year and underlying records.
4. How Will the Date Fit Your Tax and Owner-Pay Planning?
Your year-end affects when corporate income gets measured.
Your personal tax year still ends December 31.
That difference can matter for owner-managers who receive:
- salary
- bonuses
- dividends
- shareholder repayments
- other corporate payments
It does not mean one particular year-end automatically creates tax savings.
It means the year-end becomes part of the planning calendar.
For example, a September 30 corporate year-end gives the owner and accountant a different planning window than a December 31 year-end.
If owner compensation is already an important question for your corporation, TaxRecon’s previous guide on Salary vs Dividends Ontario 2027 explains why the answer depends on corporate profit, CPP, RRSP room, cash needs, payroll responsibilities, and the way payments are recorded.
Do not pick a fiscal year-end solely because someone tells you it creates a tax trick.
Pick a date that works operationally first, then consider legitimate tax-planning implications within that structure.
5. Will Your Other Reporting Periods Be Easy to Manage?
Your corporate tax year is not the only reporting cycle your business may have.
Depending on the business, you may also deal with:
- GST/HST returns
- payroll remittances
- T4 reporting
- T5 reporting
- budgeting
- management reports
- inventory cycles
- lender reporting
- shareholder reporting
Not every deadline needs to fall on the same day.
But creating a financial calendar that nobody can follow is not helpful either.
If GST/HST is already part of your business, year-end choices should be reviewed alongside your sales-tax setup and reporting method.
TaxRecon’s guide to the GST/HST Quick Method vs Regular Method is an example of how fiscal-year information can matter beyond the T2 itself.
December 31 vs a Non-Calendar Year-End
There is no universal winner.
| Factor | December 31 Year-End | Non-Calendar Year-End |
| Easy date to remember | Strong | Depends on date |
| Matches personal tax calendar | Yes | No |
| First year may be very short | Possible | Easier to avoid |
| Can avoid your peak business season | Sometimes | Often |
| Owner-pay planning window | Calendar aligned | Different planning cycle |
| Accounting workload | Falls into busy tax season | May spread workload |
| Seasonal business fit | Depends on business | Can fit operating cycle |
| Changing later | CRA approval generally required | CRA approval generally required |
December 31 may make sense when:
- the business operates evenly throughout the year
- calendar-year reporting feels easier
- owners prefer corporate and personal tax planning around similar periods
- December is not operationally difficult
- the first fiscal period will not be unreasonably short
Another date may make more sense when:
- your busiest months occur near December
- the business has clear seasons
- inventory is much easier to count at another point
- you incorporated late in the calendar year
- another month produces cleaner receivable, payable, or project balances
- you want more operating history before the first year-end
Should You Make the First Fiscal Year as Long as Possible?
Sometimes. Not automatically.
A longer first fiscal period can postpone the corporation’s first year-end accounting and T2 filing.
That can be useful for a new business that incorporated just before operations began.
It can give the business more time to:
- start trading
- establish bookkeeping
- build revenue
- organize records
- understand its cost structure
- make early business decisions before the first full year-end review
CRA also states that most corporations do not have to make regular corporate tax instalments during their first tax year, although any balance owing still has to be paid by the applicable balance-due date.
But stretching the first period close to the 53-week maximum should not override more important business considerations.
Example
Suppose a corporation is incorporated October 15, 2026.
Option 1: December 31, 2026
First fiscal period:
October 15 to December 31, 2026
Advantages:
- simple calendar year
- easy date to remember
- lines up with the owner’s personal calendar
Drawbacks:
- extremely short first reporting period
- first corporate year-end arrives almost immediately
- year-end work may land during a busy accounting season
Option 2: June 30, 2027
First fiscal period:
October 15, 2026 to June 30, 2027
Advantages:
- more business history before closing the books
- moves year-end away from December
- may fit businesses with slower summer operations
Drawbacks:
- may clash badly with businesses busy in June
- does not maximize the first fiscal period
Option 3: September 30, 2027
First fiscal period:
October 15, 2026 to September 30, 2027
Advantages:
- gives the corporation almost a full first year
- year-end remains comfortably within CRA’s 53-week limit
- can fit businesses that slow down after summer
Drawbacks:
- September may be poor for another industry
- corporate and personal tax periods no longer line up
The right answer depends on the business, not on which option looks longest.
How Does Your Year-End Affect Your T2 Filing Deadline?
Your corporate year-end starts the filing clock.
CRA requires corporations to file their T2 return within six months after the end of the tax year.
For month-end fiscal periods, common examples look like this:
| Fiscal Year-End | General T2 Filing Deadline |
| January 31 | July 31 |
| March 31 | September 30 |
| June 30 | December 31 |
| September 30 | March 31 |
| December 31 | June 30 |
If the due date falls on a Saturday, Sunday, or CRA-recognized public holiday, the next-business-day rule may apply.
Your Corporate Tax May Be Due Before the T2
This point deserves special attention.
The T2 filing deadline and corporate tax payment deadline are not the same deadline.
CRA says corporate income-tax balances are generally due two months after the tax year-end.
Certain qualifying Canadian-controlled private corporations may have a three-month balance-due date when the applicable conditions are met.
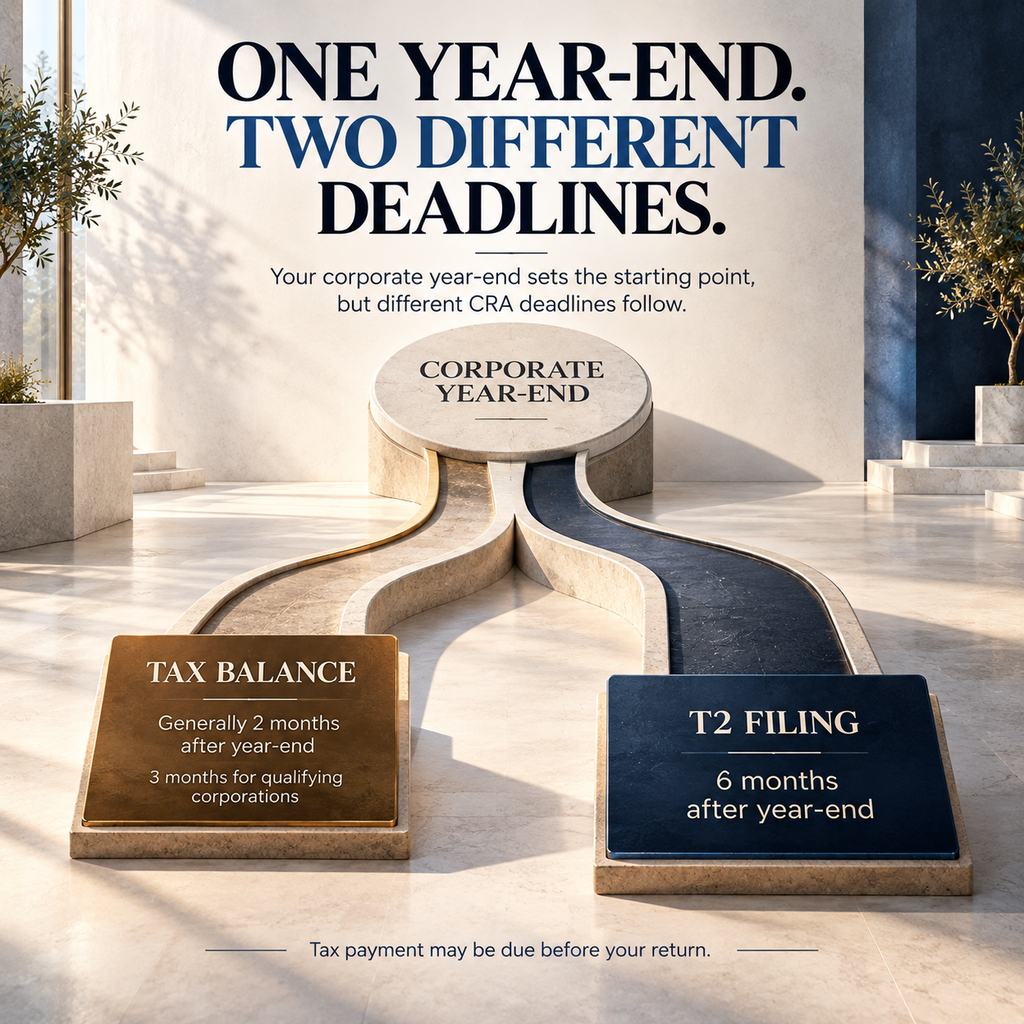
So a corporation with a June 30 year-end may have:
Year-end: June 30
Possible balance due: August 31 or September 30 depending on the corporation’s circumstances
T2 filing deadline: December 31
This catches new corporation owners because six months sounds like the only deadline.
It is not.
Your year-end creates several future dates, not just one.
The Year-End Decision Changes More Than One Date
Think of the corporate year-end as the anchor point for an annual cycle.
Before year-end
You may review:
- bookkeeping completeness
- revenue and expenses
- shareholder balances
- owner compensation
- capital purchases
- accrued expenses
- tax estimates
At year-end
You close the financial reporting period.
Two or three months later
Corporate tax may be due depending on the corporation’s circumstances.
Six months later
The T2 filing deadline generally arrives.
Then the cycle begins again.
A good year-end places that sequence somewhere you can realistically manage every year.
Is December 31 a Bad Corporate Year-End?
No.
December 31 gets criticized too easily.
For some corporations, it is the most practical choice.
It gives you:
- a familiar reporting period
- direct calendar-year comparisons
- easier alignment with personal planning
- simpler communication with owners who think in calendar years
The problem is not December 31 itself.
The problem is choosing it automatically.
December 31 can be awkward when:
- December is your highest-volume month
- inventory peaks at year-end
- seasonal staffing is heavy
- customer collections are unusually complex
- you incorporated late in December and create a very short first tax year
- your accountant’s year-end workload affects the practical service timeline
Business fit should decide the date.
Not a habit.
Are There Situations Where You Cannot Freely Choose?
Yes.
One notable CRA exception applies to a professional corporation that is a member of a partnership and carries on business in Canada.
CRA states that this type of professional corporation must have a December 31 year-end.
Other structural events can also create special tax-year rules, including certain:
- amalgamations
- acquisitions of control
- wind-ups
- changes in corporate status
If your company is part of a more complicated corporate structure, do not apply the simple first-year rule without checking whether another provision changes the answer.
Can You Change Your Corporate Year-End Later?
Usually, not just because another date suddenly looks more convenient.
CRA generally expects the corporation’s established tax year to continue from year to year.
If you later want to change it, CRA normally requires you to write to the appropriate tax services office, request approval, and explain:
- why the change is being requested
- the effective date
CRA may allow changes without prior approval in certain specific circumstances, such as some wind-ups, changes in control, or changes in corporate status.
This is why the first-year decision deserves thought.
You have much more freedom before the year-end becomes established than after.
TaxRecon’s Business Advisory Services include startup planning and business decision support where financial timing and future obligations form part of the decision.
What Do New Corporation Owners Commonly Get Wrong?
They assume December 31 is mandatory
For most ordinary new corporations, it is not.
CRA generally permits a first fiscal period of up to 53 weeks.
They confuse 53 weeks with 12 months
The maximum is 53 weeks, or 371 days, not simply “choose the same date next year.”
Watch the actual permitted period.
They pick the longest date without considering seasonality
Delaying the first year-end can be useful.
But a year-end in the middle of your busiest month may create problems every year after that.
They think the T2 and tax payment share one deadline
They do not.
The T2 is generally due within six months, but corporate tax may be payable sooner.
They ignore their bookkeeping cycle
A fiscal year-end only works well when the books can actually be closed.
They choose for tax reasons only
Tax planning matters, but a small timing benefit should not leave the business with a poor reporting date for years.
They assume they can change it whenever they want
CRA approval is generally required once the fiscal period is established.
Use This Year-End Decision Checklist
Before selecting your first year-end, write down the answers to these questions.
Incorporation
- What was the incorporation date?
- What is the latest date allowed within 53 weeks?
- Would an earlier month-end create an unreasonably short first period?
Operations
- Which months are busiest?
- Which months are quietest?
- When is inventory lowest?
- When are major projects normally completed?
Accounting
- When will receivables and payables be easiest to review?
- Are there seasonal payroll spikes?
- Will bookkeeping records be current at that point?
- Does the business have complicated inventory or project accounting?
Tax
- When would the T2 become due?
- When could the corporate tax balance become due?
- How will the date fit owner compensation planning?
Administration
- What GST/HST reporting cycle does the corporation expect?
- Are lenders or investors likely to request specific reporting?
- Will management reporting be easier on a calendar or non-calendar basis?
Then compare two or three realistic year-end dates.
Do not compare twelve.
The strongest choice usually becomes clearer once you put the business cycle beside the tax calendar.
A Simple Decision Rule
Choose the date that gives you the best combination of:
enough first-year operating time + a manageable business period + clean accounting records + practical future deadlines
If one date offers a small tax-timing benefit but creates accounting pressure every year, it may not be the better date.
If another date gives you the longest possible first year but lands in the middle of your busiest season, reconsider it.
Your corporate year-end repeats.
Treat it like a recurring business decision, not a one-time filing preference.
When Should You Ask for Professional Input?
A year-end review is worth considering before the first T2 is filed when:
- you incorporated late in the calendar year
- your business is highly seasonal
- the corporation has inventory
- you operate through several corporations
- the corporation is part of a partnership
- owner salary and dividends will be significant
- GST/HST reporting needs attention
- there are several shareholders
- you expect major financing or reporting requirements
- you are unsure which first fiscal period has already been established
Waiting until the first return is almost complete can limit your options.
The year-end should ideally be discussed while there is still time to compare dates against the way the business actually works.
Final Thoughts
Your corporation does not need the same year-end as everybody else’s corporation.
It needs a date that fits its own reporting cycle.
For most new businesses, the strongest corporate year end Canada decision starts with four facts: the incorporation date, the operating cycle, the state of the accounting records, and the deadlines the chosen date will create.
CRA gives most new corporations meaningful flexibility in the first year. Use that flexibility carefully because changing an established year-end later can require approval.
Do not pick December 31 simply because it is familiar.
Do not push the date as far out as possible simply because you can.
Choose the date you will still be comfortable closing the books in three, five, or ten years from now.
Need Help Choosing Your First Corporate Year-End?
The right date should work for more than the first T2.
TaxRecon can review your incorporation date, expected business cycle, reporting responsibilities, bookkeeping setup, owner-pay plans, and future tax deadlines before the corporation’s first year-end becomes part of its regular annual cycle.
Start with the date the corporation was formed and how the business actually operates. The filing calendar should fit the business, not fight it.
Frequently Asked Questions
What is the best corporate year-end in Canada?
There is no single best date. The strongest choice usually falls within CRA’s 53-week first-year limit, avoids the business’s busiest period where possible, provides enough time for the first operating period, and creates practical bookkeeping, tax, and reporting deadlines.
Can a corporation choose any fiscal year-end in Canada?
Most new corporations can choose a first year-end within 53 weeks of incorporation. Some exceptions apply. For example, CRA requires a professional corporation that is a member of a partnership and carries on business in Canada to use December 31.
Is December 31 the easiest corporate year-end?
It can be. December 31 aligns with the calendar year and can simplify personal and corporate planning. It may be less practical for seasonal businesses, companies with heavy December inventory or sales, or corporations incorporated close to year-end.
When is the first T2 due after incorporation?
The T2 is generally due six months after the corporation’s chosen tax year-end. The corporate tax balance may be due earlier, generally two months after year-end or three months for certain qualifying CCPCs.
Should I choose the longest possible first fiscal year?
Not automatically. A longer first fiscal period may delay the first year-end and give a startup more operating history, but business seasonality, accounting workload, tax planning, and future annual deadlines can matter more.
Can I change my corporation’s year-end later?
Usually only with CRA approval unless a specific exception applies. CRA generally asks for the reason for the requested change and the date it should take effect, so choosing carefully in the first year is easier than trying to fix a poor date later.