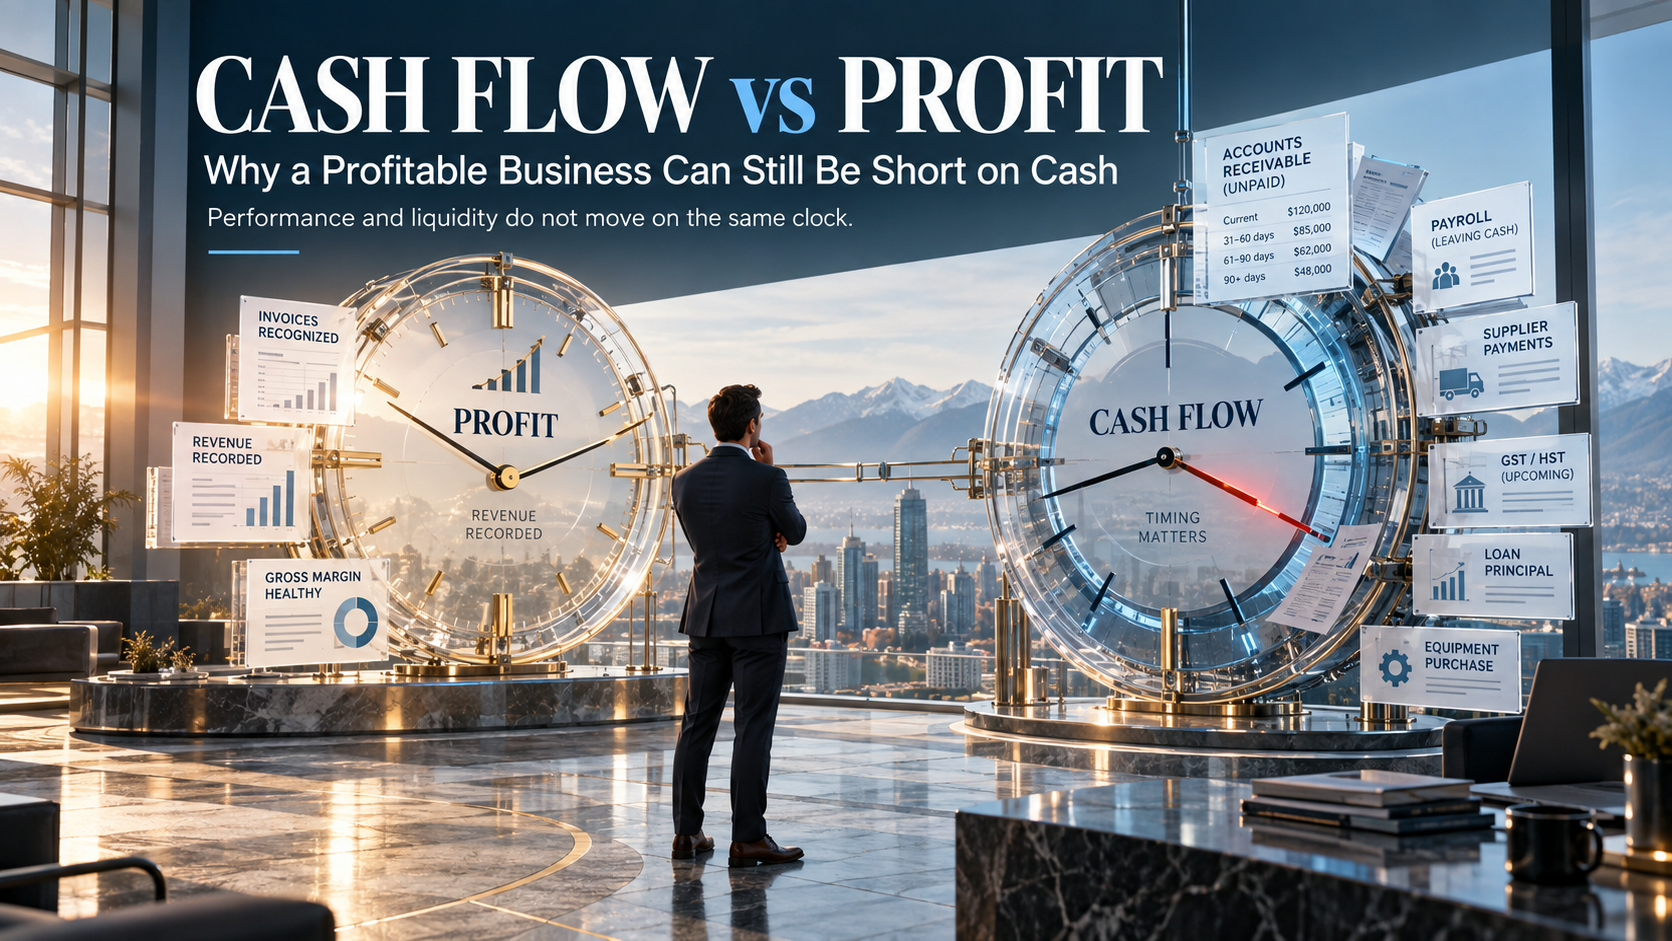
Your profit and loss statement says the business made money.
Your bank account says, “Not enough for everything due this week.”
Both can be right.
That disconnect is the real cash flow vs profit problem. Profit tells you how the business performed over a period. Cash flow tells you when money actually entered and left the business.
The difference becomes painful when payroll, suppliers, loan payments, GST/HST or another obligation comes due before the cash connected with your sales reaches the bank.
This is why TaxRecon’s financial management services keep profit, cash flow, budgets and forecasts visible as separate but connected parts of the financial picture.
Key Takeaways
- Profit does not tell you how much cash is available today.
- Timing differences between invoices, collections and payments can make a profitable business cash-poor.
- Inventory, equipment purchases and loan principal can consume cash without reducing profit by the same amount at the same time.
- The best way to understand the gap is to connect your income statement, balance sheet and cash movements rather than watching one report alone.
What Is the Real Difference Between Cash Flow and Profit?
Profit measures whether revenue exceeds the costs and expenses recognized for a period. Cash flow measures the actual movement of money into and out of the business. A company can therefore report a profit before customers have paid, while cash may already have left for payroll, suppliers, equipment, debt or taxes.
That timing difference changes everything.
The Government of Canada describes an income statement as showing whether a business earned a profit or suffered a loss during a period. Its business-planning guidance describes cash flow as showing whether enough money will be available to meet the business’s needs month by month. Read the Government of Canada business-planning guidance
Here is the practical distinction:
| Question | Profit answers | Cash flow answers |
| Did the business earn more than its recognized expenses? | Yes | Not directly |
| Has the customer actually paid? | Not necessarily | Yes |
| Can we cover Friday’s payroll? | Not necessarily | This is the relevant question |
| Does a loan create profit? | No | It can increase cash |
| Does loan principal reduce profit? | Usually no | It reduces cash |
| Does buying equipment use cash immediately? | Yes, but profit treatment can occur over time | Yes |
| Can sales growth make cash tighter? | Profit may improve | Cash can still fall |
Profit is about performance.
Cash flow is about timing and liquidity.
You need both.
The Two-Clock Test: Why the Numbers Stop Moving Together
The easiest way to understand the gap is to picture your business running on two clocks.
Clock 1: The profit clock
The profit clock asks when revenue is earned and when costs or expenses belong to the reporting period.
Send a customer an invoice today under accrual accounting and the sale may already contribute to revenue, even if the customer does not pay for another 30 or 60 days.
Clock 2: The cash clock
The cash clock waits for the money to move.
The sale does not improve available cash until the customer pays.
Likewise, some cash movements never affect current profit in the same way. Borrowing money puts cash in the bank but is not sales revenue. Repaying loan principal takes cash out but is not normally an operating expense on the income statement.
When the two clocks move at different speeds, profit and cash separate.
That is the idea to remember.
Where Does the Cash Go When the Business Is Profitable?
Usually, it did not “disappear.”
It moved somewhere the profit figure does not fully show.
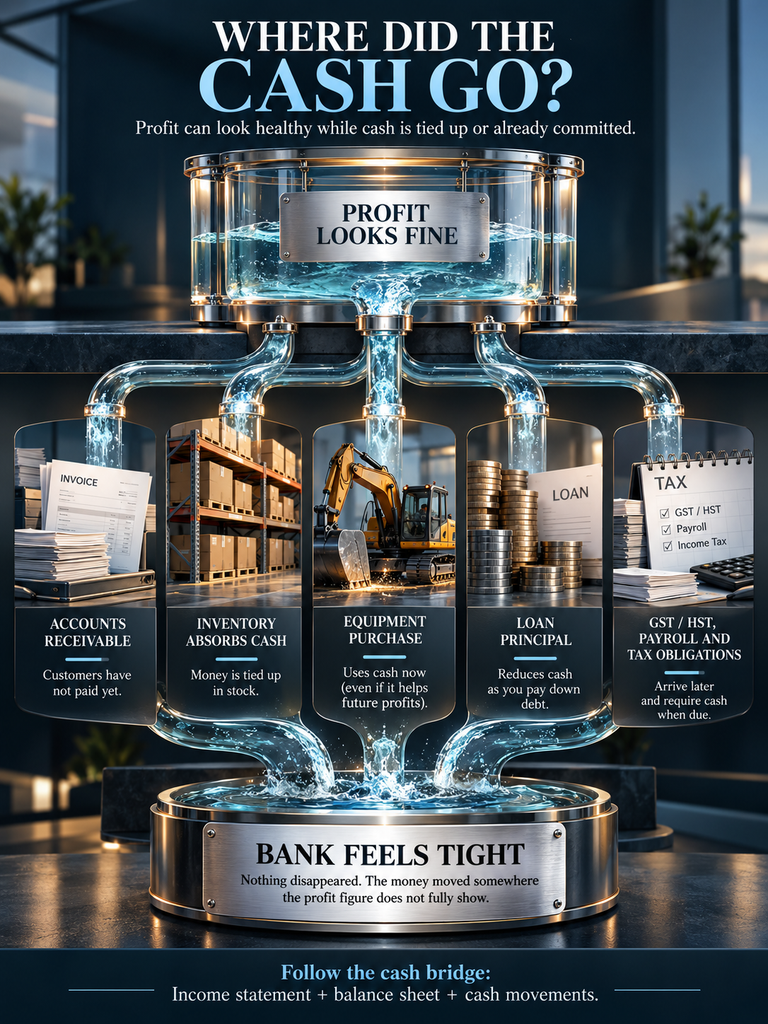
Customers have not paid yet
Accounts receivable may be one of the biggest reasons.
Suppose you complete $50,000 of work this month and invoice the clients.
The revenue can contribute to profit before all $50,000 appears in your bank account.
Meanwhile, staff, rent, suppliers and other operating costs still need payment.
The business can therefore report a good month while financing its customers’ payment terms.
Inventory absorbs money before it becomes an expense
A retailer may buy inventory ahead of a busy season.
Cash leaves immediately.
But the entire inventory purchase does not necessarily hit the profit and loss statement as an expense at that moment. The cost follows the accounting treatment of the inventory as goods are sold.
The shelves may therefore be full while the bank balance is thinner.
Equipment uses cash now
Buying a vehicle, machine or computer can create a large cash outflow.
Accounting treatment for the asset happens differently over time.
The business can remain profitable while a major equipment purchase reduces available cash sharply.
Loan principal leaves the bank
Loan payments often contain both principal and interest.
Interest can affect profit.
Principal reduces the loan balance and cash, but it is not simply another operating expense.
That means debt repayment can create a noticeable difference between reported profit and the bank balance.
Tax obligations may arrive after the profitable period
Corporate tax, GST/HST, payroll source deductions and other amounts can become cash obligations on a timetable that does not match the month in which profit was earned.
Money sitting in the bank may already have a job.
Available bank balance and genuinely free cash are not always the same thing.
One Profitable Month, Two Very Different Stories
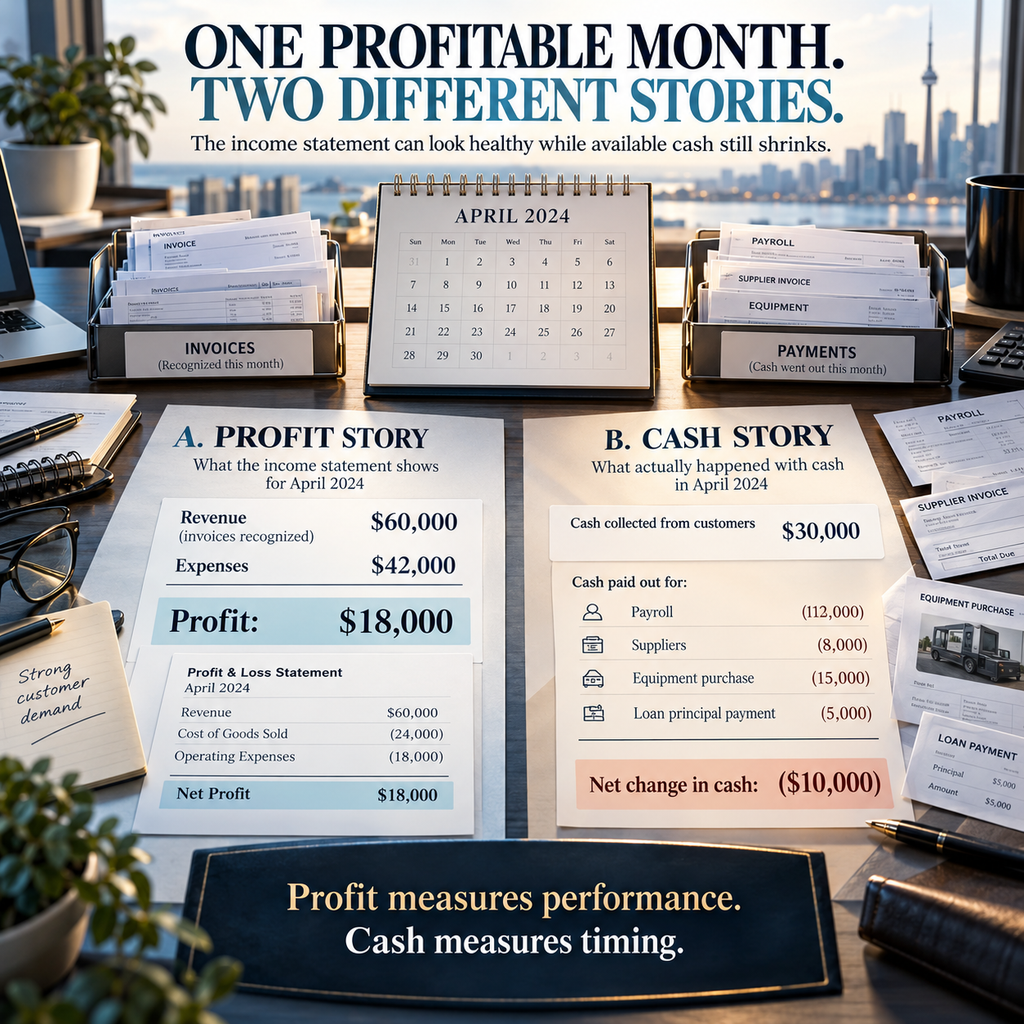
Consider this illustrative Canadian service business.
During the month, it completes $60,000 of client work.
Recognized operating expenses total $42,000.
The income statement therefore shows:
$60,000 revenue – $42,000 expenses = $18,000 profit
That looks healthy.
But only $30,000 of the customer invoices have actually been collected.
During the same period, the business pays operating bills, makes a loan-principal payment and buys equipment.
The owner is now looking at two different stories:
Profit story
Revenue exceeded recognized expenses.
Profit: $18,000
Cash story
Only part of the invoiced revenue reached the bank, while several cash commitments had to be paid immediately.
The business can therefore be profitable and still end the period with less available cash.
Nothing about those statements is contradictory.
They measure different things.
Growth Can Make the Cash Gap Bigger, Not Smaller
More sales sound like the obvious cure for cash pressure.
Sometimes growth makes it worse first.
Imagine customer orders rising quickly.
You may need to:
- hire staff before collecting from new clients
- buy materials before completing the work
- carry more inventory
- spend more on delivery or production
- offer customers payment terms
- increase deposits with suppliers
- make larger GST/HST or payroll payments later
Revenue and profit may climb while the business needs more working capital to support the larger operation.
BDC makes this connection clearly in its working-capital guidance. Senior Business Advisor Nicolas Fontaine says:
“Not having access to working capital will impact your ability to grow your company.”
Growth is therefore not only a sales question.
It is also a cash-timing question.
Why This Matters for Canadian Businesses Right Now
Cash pressure is not an abstract finance-class problem.
Statistics Canada’s September 2026 rural and small-town business data shows that, among businesses in that group that said they could not take on more debt, 43.2% cited cash flow as a reason. View the September 2026 Statistics Canada business dashboard
That statistic applies specifically to the rural and small-town business population measured by Statistics Canada, not every Canadian business.
The practical lesson is broader: profitability alone does not settle a liquidity question.
Three Reports Tell Three Different Parts of the Story
Business owners often look only at the profit and loss statement because it feels easiest to understand.
For cash questions, that is not enough.
Income statement: Did the business make money?
The income statement shows revenue, expenses and profit or loss over a period.
Use it to understand profitability, margins and operating performance.
Balance sheet: Where is the money tied up?
The balance sheet can reveal the bridge between profit and cash.
Look at:
- accounts receivable
- inventory
- accounts payable
- loans
- tax balances
- other current assets and liabilities
A growing receivable balance can explain why sales look strong while collections lag.
Cash flow information: Where did the money actually move?
Cash flow analysis follows the money itself.
It can separate cash connected with operations from money used for investing activities or financing.
If you are not sure where bookkeeping ends and financial analysis begins, TaxRecon’s guide to bookkeeping vs accounting for small businesses explains the distinction.
Reliable analysis still depends on reliable records. TaxRecon’s bookkeeping services provide the transaction and reconciliation foundation that financial reporting depends on.
Follow the Cash Bridge When Profit Looks Fine but the Bank Does Not
Do not begin by cutting expenses randomly.
Trace the difference.
Step 1: Start with net profit
Use the same period on your income statement and cash review.
Do not compare quarterly profit with today’s bank balance and expect them to match directly.
Step 2: Check unpaid customer invoices
Look at accounts receivable and its age.
Ask how much reported revenue is still waiting to become cash.
Step 3: Check inventory and major purchases
Identify cash that moved into stock, equipment or other assets.
Ask whether those payments reduced cash before they fully affected reported profit.
Step 4: Check debt and tax payments
Separate loan principal from interest.
List upcoming corporate tax, GST/HST, payroll and other obligations that may not be obvious from a casual look at monthly profit.
Step 5: Look forward, not only backward
Build a short-term cash forecast.
Map when money is expected from customers against payroll, suppliers, rent, debt and tax obligations.
TaxRecon’s earlier guide on aligning financial planning with business goals provides a wider planning context when cash requirements connect with hiring, investment or growth decisions.
What Most Business Owners Get Wrong About Cash Flow vs Profit
“Profit means the money should be in the bank”
Not if customers have not paid yet.
Profit can include revenue that has been earned but is still sitting in receivables.
“Sales growth will fix the cash problem”
Not automatically.
Growth can create more receivables, inventory, payroll and supplier commitments before the related customer cash arrives.
“Borrowing improves profitability”
Borrowing provides cash.
It does not turn loan proceeds into operating revenue.
“Paying down debt should reduce profit by the whole payment”
Not usually.
Principal and interest have different accounting effects.
“The bank balance tells me whether the business made money”
It does not.
Cash can come from loans, owner investment or asset sales. A strong bank balance can therefore coexist with a loss.
Do this: ask what caused cash to increase or decrease.
Not that: assume the direction of the bank balance proves whether the business was profitable.
When Should Cash Flow Become a Management Priority?
Do not wait until the account is almost empty.
Cash deserves closer attention when:
- invoices are taking longer to collect
- payroll is becoming difficult to time
- supplier balances keep growing
- borrowing is funding ordinary operating costs
- sales are growing faster than available cash
- inventory is increasing
- tax payments keep feeling unexpected
- major hiring or equipment decisions are approaching
This is where financial management moves beyond producing reports.
A forecast can show when the pressure may arrive before the bank balance reaches the problem point.
TaxRecon’s financial-management work covers cash-flow monitoring, budgets, forecasts, financial reporting and performance review so the business can see what changed, what is coming next and which number deserves attention.
Final Thoughts
Profit tells you whether the business model produced a financial return over a period.
Cash tells you whether the business has the money to meet the next obligation.
That is why cash flow vs profit should never become an either-or debate.
A healthy business needs profitability over time and enough liquidity to keep operating while that profit turns into cash.
When the P&L says the business is doing well but the bank account keeps creating stress, stop asking where the profit “went.”
Start tracing when the cash arrived, where it moved and what still has to be paid.
For a connected view of bookkeeping, cash flow, forecasts and financial reporting, visit TaxRecon.
Frequently Asked Questions About Cash Flow vs Profit
Why is my business profitable but there is no money in the bank?
Profit can be recorded before the related cash arrives. Customer invoices may still be unpaid, while cash has already gone toward payroll, suppliers, inventory, equipment, loan principal or taxes. Compare receivables, major cash purchases and liabilities with the profit figure to find the difference.
Which is more important, cash flow or profit?
Both matter for different reasons. Profit helps show whether the business is financially viable over time. Cash flow shows whether enough money is available when bills become due. A business needs enough cash to keep operating while also producing profit over the longer term.
Can a business have positive cash flow and still make a loss?
Yes. Cash can come from borrowing, owner investment, selling assets or collecting older receivables. Those inflows may increase the bank balance without making the current period profitable. Positive cash movement therefore does not automatically mean the company’s operations produced a profit.
Does accounts receivable count as profit?
Revenue connected with a receivable may contribute to profit before the customer pays, depending on the accounting basis and transaction. The receivable itself represents money owed to the business. Until collection occurs, it has not become cash available in the bank.
Does buying inventory reduce profit immediately?
Not necessarily by the full purchase amount. Inventory is generally recorded as an asset until the related goods are sold, at which point the associated cost flows through the profit calculation. Cash, however, may leave much earlier when the inventory is purchased or the supplier is paid.
Does taking out a business loan increase profit?
No. Loan proceeds increase cash and create a liability rather than ordinary sales revenue. The later loan payments also need to be separated between principal and interest because those components do not affect the income statement in the same way.
Is a cash flow statement the same as a profit and loss statement?
No. The profit and loss statement reports revenue, expenses and profit over a period. Cash flow information tracks actual sources and uses of cash. Reviewing both, together with the balance sheet, helps explain why reported profit and the bank balance can move differently.
How often should a small business review cash flow?
The right frequency depends on the business and how tight its cash position is. Businesses with fast growth, large payrolls, seasonal sales, slow-paying clients or major upcoming payments may need frequent cash reviews. The forecast should be updated when meaningful assumptions change.
Can better bookkeeping fix a cash flow problem?
Bookkeeping cannot create cash, but better records can show where cash is tied up or moving unexpectedly. Current reconciliations, receivables, payables and liability balances give the business a more dependable foundation for forecasting and deciding what operational change may be needed.
Can TaxRecon help if my profit looks healthy but cash is tight?
Yes. TaxRecon’s financial-management scope includes cash-flow monitoring and forecasting, budgeting, financial statements and performance reporting. Where the underlying books are incomplete or unreliable, bookkeeping may need attention first so the cash and profit analysis starts from records that can be explained.
Know Why the Profit and Bank Balance Are Telling Different Stories
When profit looks strong but cash keeps feeling tight, another income statement is not always the answer.
TaxRecon can help connect the bookkeeping, receivables, payables, cash commitments and forecast so you can see where the gap is coming from and what needs attention next.